Reddit’s ads are growing faster than its audience
In short
- Reddit’s ad revenue grew 74% and then 64% in the first two quarters of 2026, yet the stock ended about flat (−1%) while the Nasdaq-100 rose 33%.
- The reason is the audience: US daily users fell in the June quarter as Google sent fewer visitors, and Reddit stopped reporting the logged-in figures that showed loyal use.
- App growth and a larger Google licensing deal could fix that, but neither is in reported results yet, so I treat the ad strength as necessary but not enough.
Reddit is earning more from each visitor while becoming less sure how many visitors it will have. Through 2026 its advertising grew faster than almost anyone’s in online ads, and the stock still finished about where it started. The audience those ads are sold against depends heavily on Google, and on AI chatbots that may or may not send people back.
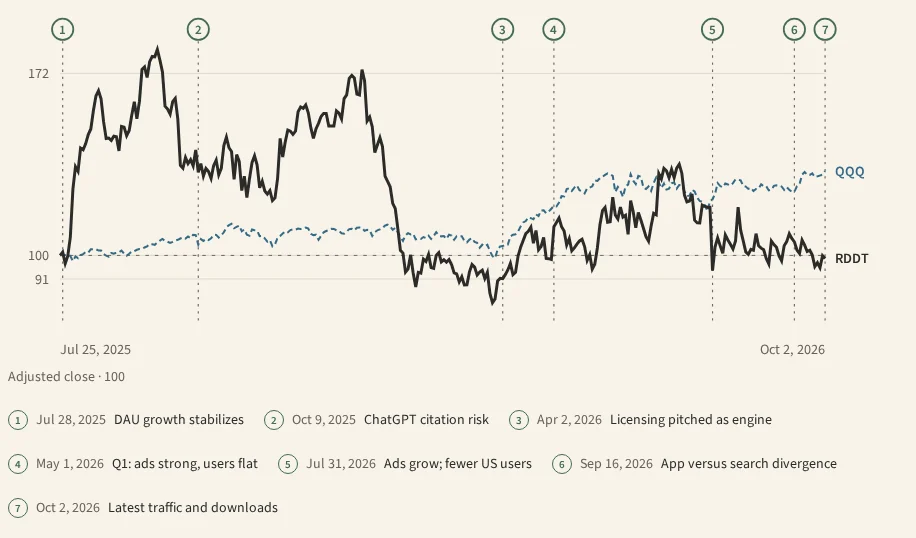
The chart sets Reddit and QQQ, the Nasdaq-100 fund, to 100 on Jul 25, 2025. Over the full period Reddit fell 1.2% while QQQ rose 33.1%. Earnings days set the path. On May 1, first-quarter results with ad revenue up 74% sent the stock up 14%, and it gained 21% from the end of April to the end of July. On Jul 31, second-quarter results beat again on revenue, but US daily users fell and the stock dropped 14%. Being added to the S&P 500 gave it an 11% lift in mid-August that faded. From the July report to mid-September it was down about 9%, and it slipped further as third-party tracking turned weaker.
Analysts have been bullish on the ad engine and divided on the audience. Jefferies’ checks in July 2025 pointed to performance ads and small-business demand lifting revenue per user. RBC’s small-business checks in January were weaker, describing low prices and uneven conversions. In April Needham made Reddit a top pick on the idea that it is becoming a human-verified source for AI, cited in more than 35% of AI answers, and estimated that its roughly $60 million a year from each of OpenAI and Google could double. Wells Fargo in September estimated a new Google deal could be worth $250–300 million a year from 2027, while arguing that Google’s new payments to publishers lower the odds of favorable terms.
The advertising improvement is real and not much in dispute. In the March quarter revenue was $663 million, up 69%, and ad revenue $625 million, up 74%, with more than 60% coming from performance ads that advertisers buy for measurable results. Reddit’s automated campaign product delivered 17% lower cost per sale and 25% more conversions on average, and the number of active advertisers grew more than 75%. In the June quarter revenue was $805 million against about $730 million expected, ad revenue rose 64% and revenue per user 36%. A new Shopify integration that lets merchants load their catalogs directly widens that funnel further.
The audience depends on products Reddit does not control. In the June quarter US daily users were 53.2 million, up 6% from a year earlier but down 0.3 million from the quarter before, and both logged-in and logged-out users fell. Reddit said it would stop reporting that split, which removes the clearest measure of whether it is replacing search visitors with regular users just as that became the main question. The outside data mostly points the wrong way. Google search traffic to Reddit fell 5.9% year on year in the third quarter after rising 8.9% in the second, according to Similarweb figures cited by Guggenheim. One tracker counted Reddit’s share of ChatGPT search citations falling from 3.8% to 0.5% over a few weeks in August. And in May Google’s AI search began showing “perspectives” from forums like Reddit inside its answers, which can keep users on Google. As one investor put it in April, it is hard to think of a mid-sized internet company that worked once its user base stalled.
The fixes are plausible and not yet in the reported numbers. Guggenheim’s data showed app downloads up 47% year on year and app daily users up 38%, and the chief executive said new-user retention rose 50% last quarter. Downloads are not retention, though, and the same executive conceded that Reddit’s recommendation feed is a year to 18 months behind the best in the industry. Piper Sandler’s data showed August users up 18% year on year, but Piper also flagged a change in measurement method expected to reset the reported audience size by about 20%, so that comparison is hard to lean on. On licensing, talks with Google are active but nothing is signed, and the current deals are small next to revenue running above $800 million a quarter.
The near-term test is the next results report. Yipit’s tracking had US and international daily users heading for misses of about 1.5 million and 4.5 million; a beat would challenge that read and a miss would confirm it. I would read the user number against the change in measurement, look for any disclosure of app or logged-in use, and watch for a signed Google renewal, which RBC expects in early 2027. Until users stabilize, strong ad growth is necessary but not enough.
What to watch: Reported daily users against weak third-party tracking, and a signed Google licensing renewal.